31 Aug 2026
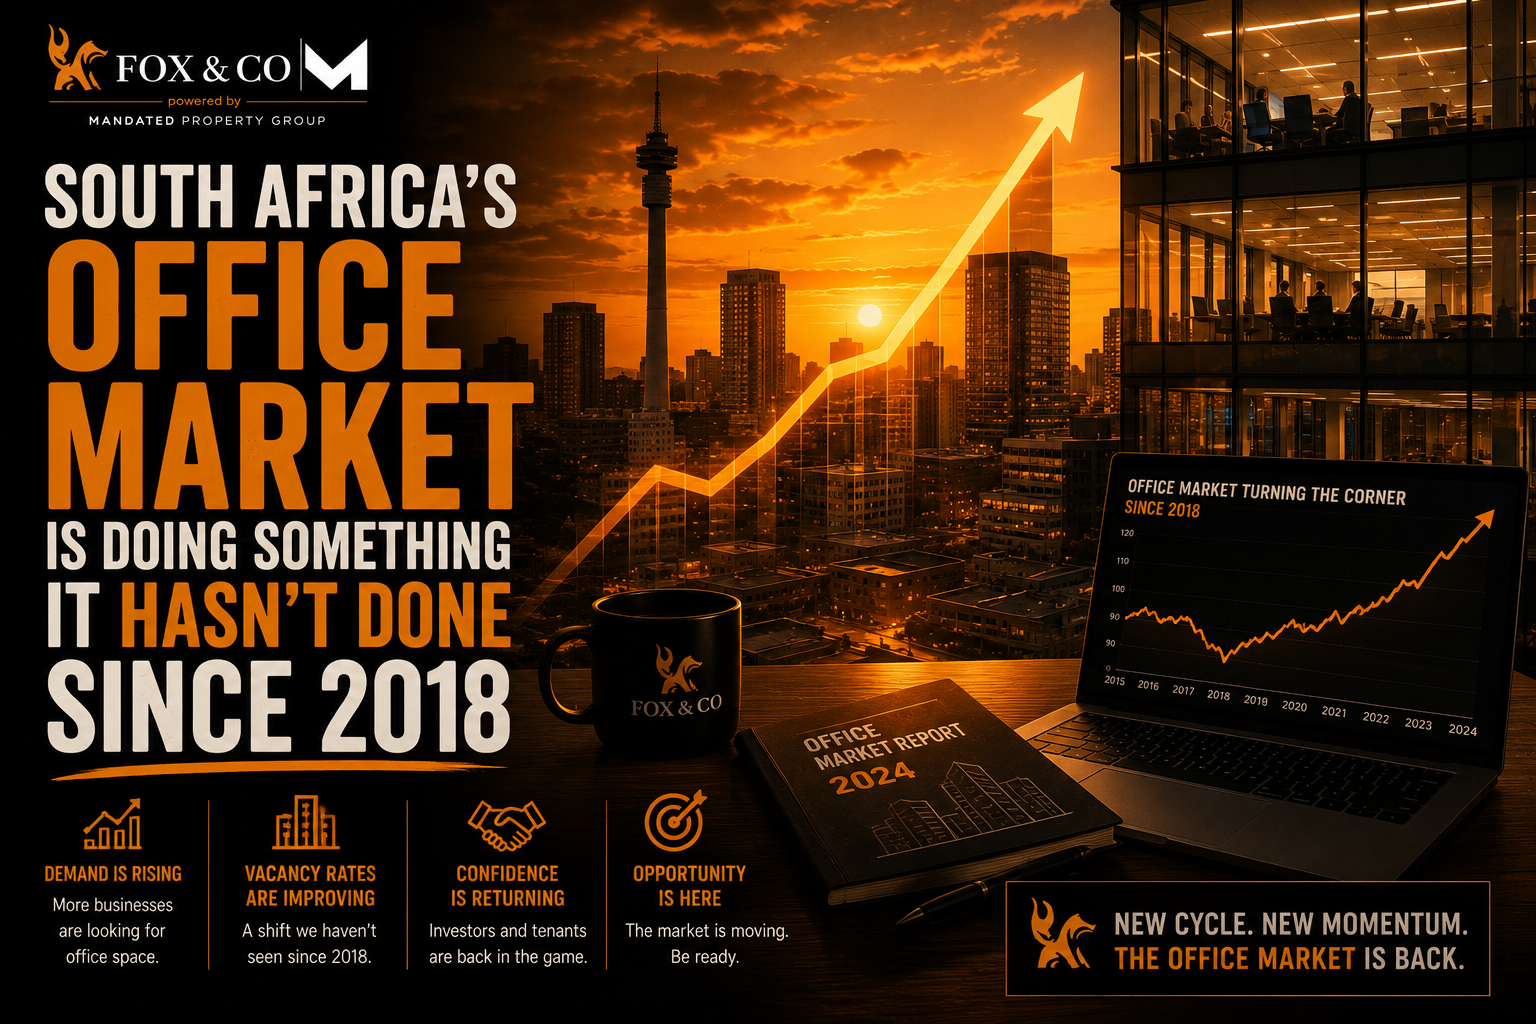
South Africa's office market is doing something it hasn't done since 2018
There is a particular kind of building that haunts South African business districts — the office tower that's clearly occupied on floors one through three, visibly dark on floors six through ten, and entirely mysterious on everything in between. You've driven past them. You've probably worked in one at some point. They've been a feature of the South African commercial property landscape for the better part of a decade, and they represent one of the sector's most persistent headaches: stubbornly high office vacancy rates that seemed to have no end in sight. Until now, apparently.
The premium and A-grade office sector — not the ageing B- and C-grade stock that's increasingly being converted into apartments, as we covered in a recent edition — is showing genuine signs of recovery. Vacancy rates in the top tier of the South African office market are on a clear downward trajectory, and the credible institutional target being set for the end of the 2027 financial year is single-digit vacancies. For context: the last time that happened was 2018. That is not a short drought. And the end of it is worth understanding.

South Africa's office vacancy problem didn't start with COVID-19, which is a point worth making clearly because it changes the recovery narrative meaningfully. Office vacancies were already rising before the pandemic — driven by a combination of oversupply that had been building for years and a domestic economy that simply wasn't generating the corporate tenant demand needed to absorb it all.
When the pandemic arrived in 2020, it accelerated a trend that was already in motion. Businesses that had been quietly reducing their footprint suddenly had compelling operational cover to do so much faster. Lease renewals were renegotiated, floors were handed back, and vacancy rates spiked to levels not seen in a generation. The national average office vacancy rate climbed into the mid-teens. Even premium-grade properties felt the pressure.
What's changed is a combination of factors that are now working in the same direction simultaneously — which is the key distinction between noise and a genuine trend shift.

The national average office vacancy rate currently sits at just over 12%. That's the broad market picture — and it's heavily skewed by the B- and C-grade stock that continues to struggle. The premium and A-grade segment of the market is performing meaningfully better, with leading institutional landlords already operating below the national average and targeting a further significant reduction over the next 12 to 18 months.

The critical distinction is between the overall market and the quality-tiered market. Premium and A-grade offices are recovering. B- and C-grade offices are, for the most part, not — and many of them are being repurposed rather than re-leased, which is itself a form of market clearing. The vacancy reduction in the premium tier is therefore happening against a backdrop of shrinking overall office supply, as the weakest stock exits the lettable pool entirely. Fewer buildings competing for tenants, plus improving tenant demand, equals falling vacancies. The arithmetic is not complicated.
The vacancy journey — a timeline that matters


Vacancy rates are the headline number, but rental reversions are where the commercial property market's true health is measured. A reversion is the change in rental rate when a lease comes up for renewal — positive means the market can command higher rents on renewal, negative means tenants are negotiating their way to lower ones.
South Africa's premium office sector has been stuck in negative reversion territory for several years — meaning that as leases expired and renewed, the rents came down rather than up. That's the uncomfortable reality of a market with too much supply chasing too little demand. The encouraging development is that the depth of negative reversions is improving. After several years of double-digit negative reversions, the trajectory is clearly pointing toward breakeven — and eventually, the positive territory that healthy, supply-constrained markets produce.
When reversions turn positive, it means landlords are negotiating from strength rather than weakness. That shift — from a tenant's market to a more balanced one — is what the current vacancy trajectory is pointing toward, and it's the mechanism through which falling vacancies convert into rising net operating income and eventually into improved property valuations.
Three forces are working simultaneously, and their combination is more powerful than any single one would be alone.
First: no new supply. There has been essentially no significant speculative office development in South Africa for several years. When you stop adding to an oversupplied market, the existing oversupply gradually gets absorbed. It's slow, but it's the only way markets self-correct when demand isn't surging.
Second: active portfolio management. The most sophisticated institutional landlords in the South African office market made early and deliberate decisions to shed their weakest assets — the B- and C-grade stock with structural vacancy problems — before those assets became a drag on portfolio performance. By concentrating into premium and A-grade assets in the best locations, these landlords positioned themselves to benefit disproportionately from the recovery in tenant demand for quality space.
Third: improving economic confidence. The broader South African economy is showing more consistent positive signals than it has in several years. Business confidence improvements translate, with some lag, into corporate decisions to expand space, upgrade offices, and commit to longer lease terms. That demand is now feeding through into the premium office market's vacancy trajectory.