5 Sept 2026
Why Logistics Is Eating South Africa's Industrial Property Market — And What It Means for Investors
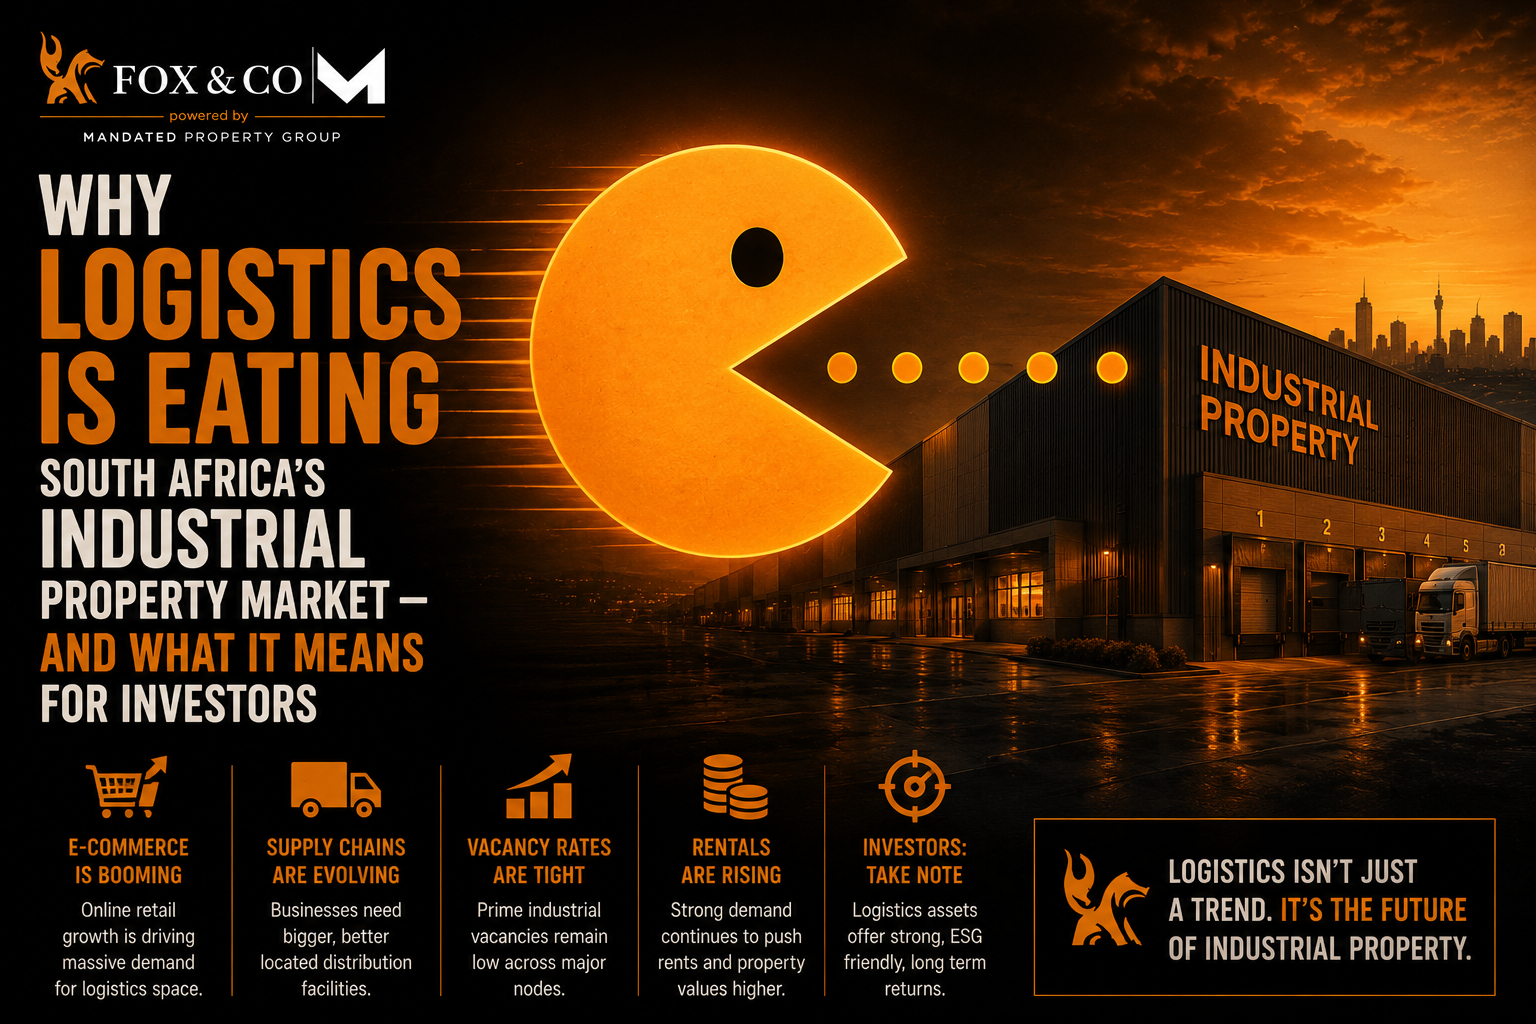
Somewhere between you clicking "buy now" and a delivery driver leaving a parcel on your doorstep twenty minutes later than promised, an entire property sector quietly reorganised itself. Warehouses, once the unglamorous back-of-house cousin of the property world — all concrete floors and roller doors, nobody's idea of a dinner party topic — have become the asset class every serious investor suddenly wants to talk about. Logistics isn't just growing within South Africa's industrial property market anymore. It's eating it.
The numbers back up the appetite. National industrial vacancy rates have dropped to somewhere between 3.8% and 4% in early 2026, among the tightest levels the sector has seen in years, with scarcity even more acute in in-demand nodes like Cape Town, where vacancy has fallen as low as 3.3%. For context, an empty industrial unit in this market isn't sitting empty because nobody wants it — it's sitting empty for roughly the time it takes an agent to update the listing photos. \

Why This Is Happening (Hint: It's Your Shopping Habit)
The primary driver is refreshingly unglamorous: South Africans have simply never stopped buying things online since they started during the pandemic, and every one of those purchases needs to be picked, packed and delivered from somewhere. That somewhere increasingly needs to be closer to the customer, better equipped, and running at a scale that a converted garage on the edge of an industrial park simply can't support anymore.
Add to that a broader restructuring of supply chains — local and international businesses reconsidering where they hold stock, how quickly they can move it, and how exposed they are to disruption — and you get a sector where modern, well-specified warehousing is being absorbed almost as fast as it's delivered. Cape Town's industrial market illustrates this well: modern logistics facilities with higher stacking capacity, larger yards, stronger power supply and solar integration are being snapped up rapidly by tenants who've decided a traditional low-eave warehouse with a gravel yard is no longer good enough.
There's a quieter driver too: energy security. Facilities with solar, battery backup and genuine power resilience are increasingly non-negotiable for logistics tenants who can't afford a distribution centre going dark mid-shift. Capital is visibly rotating away from legacy manufacturing stock and toward energy-independent, tech-enabled logistics space — the flight to quality that's reshaping retail is playing out even more decisively here.
Who's Winning: The Numbers Behind the Rush
• Rentals for 500m² industrial space grew roughly 8.4% year-on-year in 2025, comfortably outpacing inflation and giving landlords a genuine hedge against rising costs
• Cape Town rental growth has run even hotter, with some prime logistics corridors posting close to 15% year-on-year growth, and A-grade industrial rentals up as much as 58% since 2021 — properties once let around R60/m² are now achieving R90–R95/m²
• Prime industrial yields have tightened to roughly 8–9.4%, still comparing favourably to government bond yields in the low-to-mid teens, which is exactly the kind of spread that keeps institutional capital interested
• Industrial-focused REITs with strong logistics exposure are being treated as the sector's standout performers by analysts, distinguishing sharply between portfolios with modern, well-let logistics stock and those still carrying older, undifferentiated space
• In some Cape Town nodes, developers are now building speculatively — starting construction before a tenant is even secured — a level of confidence that would have been unthinkable in industrial property five years ago
Where the Action Is
Nationally, the nodes doing the heavy lifting are the ones you'd expect: strong logistics corridors with genuine transport access. In Cape Town, Airport Industria, Montague Gardens, Epping, Blackheath, Bellville South and Rivergate are running at close to zero vacancy. In Durban, land constraints are pushing demand into Riverhorse Valley and Cornubia, where premium rents are being achieved despite the geographic squeeze.
On the Gauteng side, Midrand continues to perform strongly for light-industrial and warehousing users chasing N1 corridor access, alongside established logistics hubs like Kyalami and Linbro Park. Closer to home, Jet Park — sitting right in the Boksburg industrial belt — along with Wadeville and the broader Germiston corridor, continues to benefit from exactly the same forces: proximity to major routes, existing logistics infrastructure, and tenants who'd rather pay a premium for a well-located node than gamble on something cheaper and harder to reach.
What This Means for Investors
The obvious temptation is to read "lowest vacancy in years" and assume any industrial property is a good buy. It isn't quite that simple. The market has bifurcated: modern, well-specified logistics assets with strong power resilience and genuine transport access are commanding premium rentals and tight yields, while older, lower-spec industrial stock — the kind with low eaves, limited yard space, and no meaningful power backup — is being left behind by tenants who've upgraded their expectations along with their supply chains.
• Prioritise assets with modern specifications — adequate eaves height, yard and turning space for larger trucks, and reliable power — over older stock trading at a superficially attractive price
• Factor financing costs into your yield calculations properly; with the prime lending rate sitting around 10.50%, the spread between your borrowing cost and achievable yield matters more than the headline rental growth figure
• Treat energy resilience as a specification requirement, not a nice-to-have — solar and backup power increasingly determine which buildings get let quickly and which sit vacant
• Watch node-level fundamentals closely rather than relying on national averages; a strong logistics corridor with genuine transport access will consistently outperform a generic industrial park a few kilometres off the main route
• Locally, corridors like Jet Park, Wadeville and Germiston offer some of the same fundamentals driving Cape Town's rental growth, often at a considerably lower entry price than the coastal hotspots
The Bottom Line
Logistics didn't sneak up on South Africa's industrial property market — it arrived exactly as predictably as an overnight courier, and it's not slowing down. For investors, the opportunity is real, but it isn't uniform: the yield and rental growth on offer are concentrated in modern, well-specified, well-located stock, not industrial property in general. Buy the right building in the right node, and you're riding one of the strongest-performing segments of South African commercial property. Buy the wrong one simply because it's labelled "industrial," and you may find yourself competing with buildings that were designed for a supply chain nobody's running anymore.
Frequently Asked Questions
Why is industrial property outperforming retail and office in South Africa?
Industrial property, and logistics space in particular, is benefiting from sustained e-commerce growth and supply chain restructuring, which has pushed national vacancy rates down to around 3.8–4% while rentals continue to grow well ahead of inflation.
What yield can investors expect from prime industrial property in 2026?
Prime industrial assets are currently trading at yields of roughly 8–9.4%, which remains attractive relative to government bond yields, though the spread needs to be weighed against a prime lending rate of around 10.50%.
Which areas are seeing the strongest industrial rental growth?
Cape Town has led national rental growth, with some prime logistics corridors posting close to 15% year-on-year increases. On the Gauteng side, nodes with strong transport access such as Midrand, Kyalami and the Jet Park, Wadeville and Germiston corridor continue to perform well.
Is older industrial stock still a good investment?
Older, lower-specification industrial buildings are increasingly being left behind by tenants who now expect modern eaves height, yard space and power resilience. These assets can still perform, but typically at a discount to modern logistics stock and with a longer letting period.